
Ecopmin Technologies Secures First Institutional Funding Round Valuing Company at ₹1,000 Crore
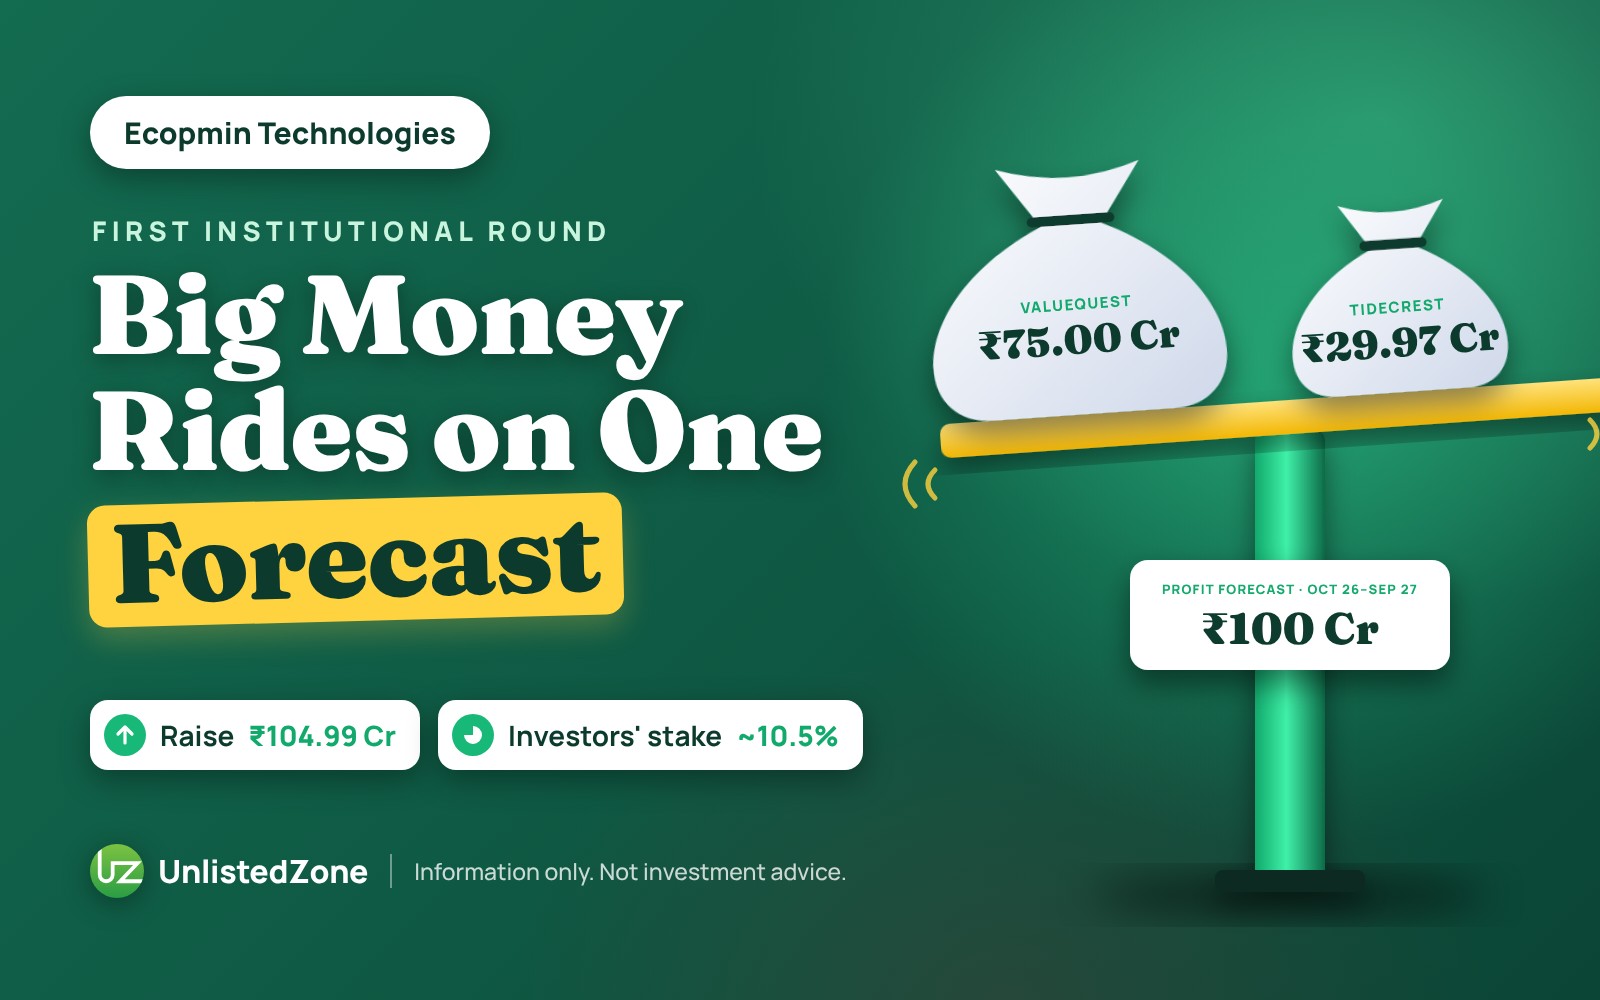
Chennai-based Ecopmin Technologies is set to raise ₹104.99 crore in its inaugural institutional funding round, achieving a post-money valuation of ₹1,000 crore. This significant capital infusion comes from ValueQuest Tristar Fund and the Dharamshi family’s Tidecrest Partners. The transaction introduces a unique profit-linked share conversion mechanism and grants specific rights to the new investors. An Extraordinary General Meeting (EGM) has been convened for November 21, 2026, to seek shareholder approval for this round, as detailed in the EGM notice dated November 16, 2026.
Investment Details
The funding round involves two investors subscribing to 28,300 Series A Compulsorily Convertible Preference Shares (CCPS) at a uniform price of ₹37,102 each.
| Investor | Type | Series A CCPS | Amount (₹ Crore) |
|---|---|---|---|
| ValueQuest Tristar Fund | Alternative Investment Fund | 20,215 | 75.00 |
| Tidecrest Partners (via Kalpraj Damji Dharamshi, Harsha Hemang Dharamshi and Paolomi Kalpraj Dharamshi) | Partnership Firm | 8,085 | 29.97 |
| Total | 28,300 | 104.99 |
ValueQuest Tristar Fund is an investment vehicle associated with renowned investor Ravi Dharamshi. Promoters and existing directors are not participating in this particular funding round.
Valuation and Profit-Linked Share Conversion
The Series A CCPS pricing of ₹37,102 per share establishes Ecopmin’s pre-money valuation at approximately ₹895 crore, escalating to ₹1,000 crore post-money. This valuation is primarily derived from management’s projection of a ₹100 crore Profit After Tax (PAT) for the fiscal period spanning October 2026 to September 2027, to which investors have applied a 10x multiple.
While a registered valuer, ValuGenius Advisors LLP, assessed the fair value at ₹20,728 per share in a November 13, 2026 report, the investors are committing capital at roughly 1.8 times this valuation, underscoring their confidence in the company’s ability to meet its ambitious profit targets. Upon conversion, investors are projected to hold approximately 10.5% of the company.
Crucially, the CCPS conversion is not fixed. The final conversion price will be recalibrated based on the actual PAT achieved between October 2026 and September 2027 (calculated as actual PAT × 10), capped at a ₹1,000 crore post-money valuation. This mechanism carries an asymmetric risk for existing shareholders:
| Scenario | Actual PAT (₹ Crore) | Post-Money Valuation (₹ Crore) | Price per Share (₹) | Investors’ Shares | Investors’ Stake |
|---|---|---|---|---|---|
| Base Case | 100 | 1,000 | 37,102 | 28,300 | 10.50% |
| Profit Falls Short | 95 | 950 | 35,029 | 29,975 | 11.05% |
| Profit Beats Target | 110 | 1,000 (capped) | 37,102 | 28,300 | 10.50% |
Should Ecopmin’s actual PAT fall short of the ₹100 crore target, investors will receive a higher number of shares, leading to increased dilution for existing shareholders. Conversely, if PAT exceeds the target, the ₹1,000 crore valuation cap means existing shareholders do not benefit from a higher valuation. The definition of profit is stringent, excluding one-off gains, subsidies, scrap sales, ESOP costs, and unrealized forex gains. A Big 4 firm will calculate this figure, with PwC or an affiliated entity conducting financial due diligence.
Utilization of Funds and Investor Rights
The EGM notice outlines three strategic uses for the incoming funds, although specific details are not provided in this overview.
The investors secure substantial governance rights under a Shareholders’ Agreement dated November 6, 2026. These include voting rights on an as-converted basis, affirmative (veto) rights on specified reserved matters, and a liquidation preference. Furthermore, no dividends can be distributed to equity holders without the written consent of the new investors. The company is adopting revised Articles of Association to formally incorporate these new terms. Despite these provisions, the EGM notice indicates that control of the company will not change. Managing Director Perumal Vinoth’s current 48.77% stake is projected to decrease to approximately 43.6% post-conversion in the base case scenario.
Cap Table Rationalization
Prior to the institutional investment, Ecopmin is streamlining its capital structure by addressing outstanding employee debentures. In August 2020, 10,000 zero-coupon convertible debentures, valued at ₹1 lakh each, were issued to five employees. Originally, these were set to convert into 10,000 equity shares, representing approximately 4% of the current equity.
Under amended terms, all five debenture holders have consented in writing to a conversion into just 10 shares, at a price of ₹10,000 per share. This modification prevents significant dilution for existing shareholders and provides clarity on the fully diluted share count for the incoming investors.
Implications for Existing Shareholders
This funding round marks a pivotal moment for Ecopmin Technologies, attracting a reputable institutional investor and validating the company with a ₹1,000 crore valuation. This serves as a strong positive signal for an unlisted entity with a considerable retail shareholder base. However, the valuation’s foundation critically depends on achieving the ambitious ₹100 crore PAT target for the year ending September 2027.
Existing shareholders should closely monitor:
- Profit Target Attainment: Any shortfall in the projected PAT will result in greater dilution of their holdings.
- Promoter Loan Repayment: A portion of the new capital may be allocated to repaying loans to promoters and related parties, potentially diverting funds from direct business growth.
- Enhanced Investor Rights: The new investors’ veto rights and requirement for dividend consent grant them significant influence over future corporate decisions.
Latest Price : https://mrgaga.in/unlisted-share