
Berar Finance Reports Strong H1 FY27 Growth with 81% Profit Surge; Credit Cost Remains Key Focus
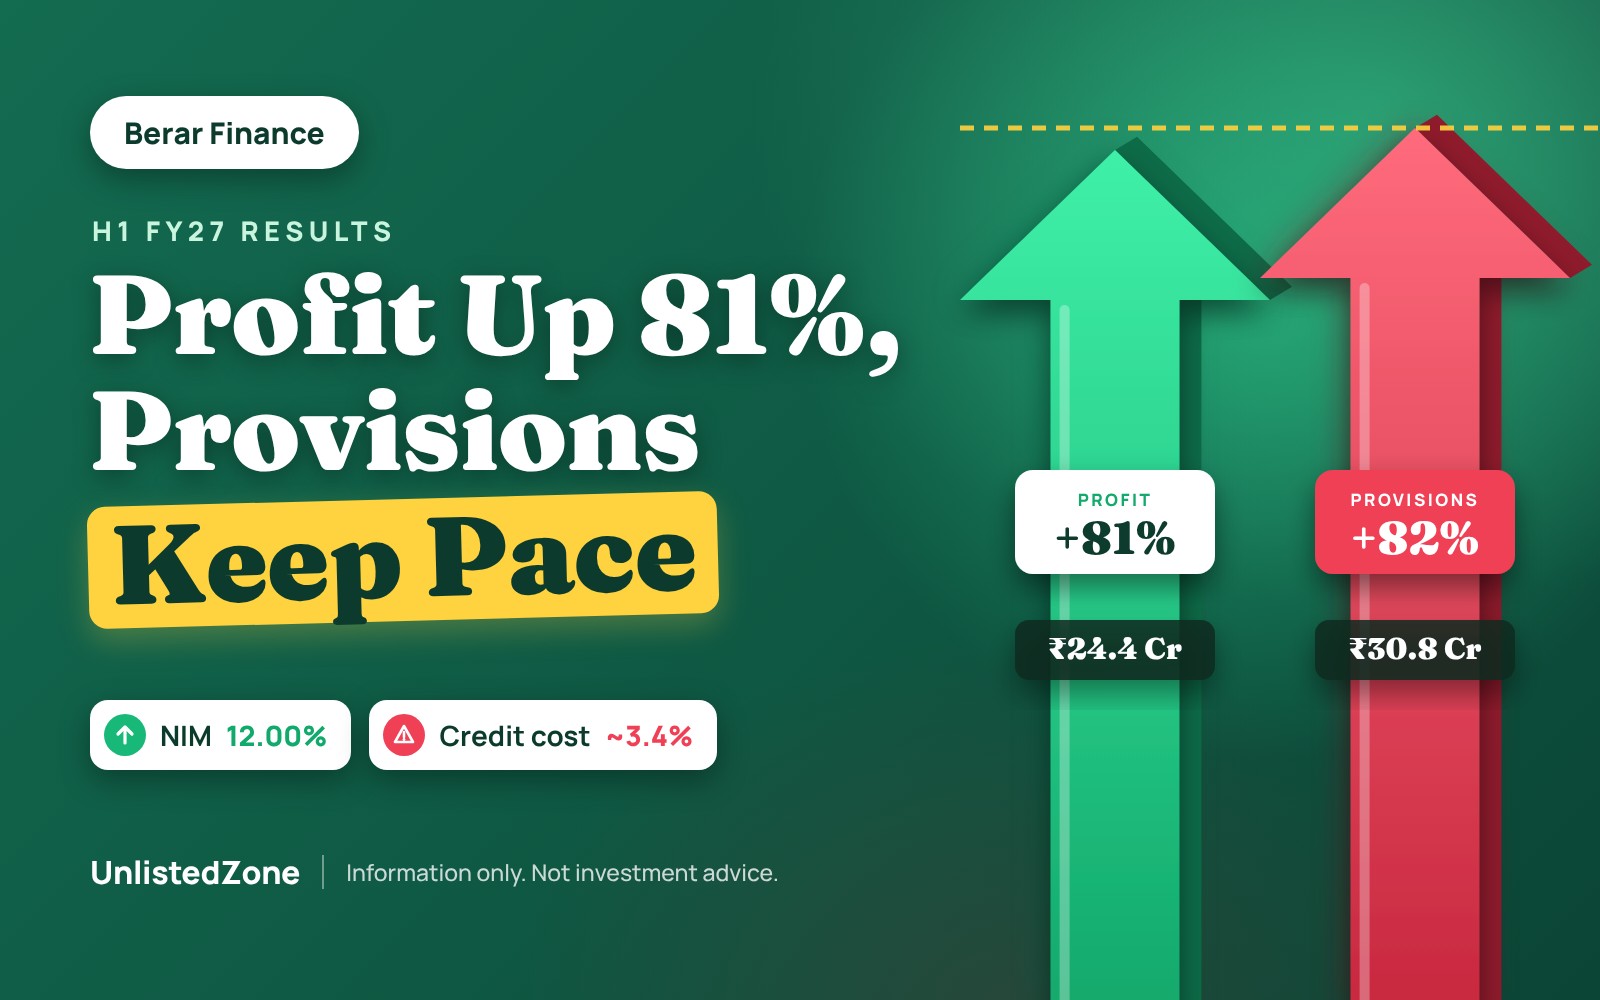
Berar Finance Limited reported a substantial 81% increase in profit after tax (PAT) to ₹24.4 crore for H1 FY27 (April–September 2026), up from ₹13.4 crore in H1 FY26. This impressive growth was primarily driven by a 48% rise in net interest income (NII) and a widening Net Interest Margin (NIM) to 12.00% from 10.62%.
Pre-provision operating profit also surged by 82% to ₹62.8 crore. However, provisions for impairment mirrored this growth, rising by 82% to ₹30.8 crore. Consequently, credit cost remains a critical metric for monitoring future profitability.
The Nagpur-based NBFC’s board approved these unaudited results on November 3, 2026. N.A. Shah Associates LLP, the statutory auditors, conducted a limited review.
H1 FY27 Financial Highlights
The first half of FY27 saw Berar Finance achieve a PAT that already represents 67% of the full-year FY26 profit of ₹36.2 crore. Total income for the period grew 33% to ₹218.9 crore.
| (₹ Crore) | H1 FY26 | H1 FY27 | Change |
|---|---|---|---|
| Interest income | 147.8 | 196.7 | +33% |
| Fee & commission income | 10.5 | 13.0 | +23% |
| Other operating and other income | 5.9 | 9.2 | +56% |
| Total income | 164.3 | 218.9 | +33% |
| Finance cost | 74.4 | 87.7 | +18% |
| Net Interest Income (NII) | 73.4 | 109.0 | +48% |
| Average loan book | 1,382.5 | 1,815.7 | +31% |
| NIM (annualised) | 10.62% | 12.00% | +1.38 pts |
| Employee cost | 36.2 | 48.5 | +34% |
| Other expenses + D&A | 19.3 | 19.9 | +3% |
| Pre-provision operating profit | 34.4 | 62.8 | +82% |
| Provisions (impairment) | 16.9 | 30.8 | +82% |
| Profit before tax | 17.5 | 32.0 | +82% |
| Tax | 4.1 | 7.6 | +84% |
| Profit after tax | 13.4 | 24.4 | +81% |
| EPS, basic (₹, not annualised) | 10.89 | 16.66 | +53% |
| Net profit margin | 8.18% | 11.13% | +2.95 pts |
Note: NII = interest income less finance cost. Average loan book = average of opening and closing loans for the half year. NIM = (NII × 2) ÷ average loan book. Pre-provision operating profit = total income less finance cost, employee cost, other expenses, and D&A. EPS grew slower than PAT due to a rise in share count from 1.23 crore to 1.45 crore after a capital raise.
Income and Operational Efficiency
NII expanded significantly by 48% as interest income grew 33%, outperforming the 18% increase in finance cost. This divergence in borrowing and lending cost growth contributed to the NIM widening to 12.00% on an average loan book that expanded by 31% to ₹1,815.7 crore. NII growth outpaced the average loan book expansion, signaling improved profitability per unit of lending.
Fee income increased by 23% to ₹13.0 crore, while other operating income saw a robust 56% rise to ₹9.1 crore. However, the recurring nature of this ‘other operating income’ line item warrants closer observation.
Operational efficiency improved considerably, with operating expenses (Opex) as a percentage of net income (total income less finance cost) decreasing to 52.1% in H1 FY27 from 61.7% in H1 FY26. Employee costs, the largest operating expense after interest, grew 34% to ₹48.5 crore, while other expenses and depreciation & amortization (D&A) remained nearly flat (+3%).
Asset Quality and Provisions
Provisions for impairment increased by 82% to ₹30.8 crore, absorbing 49.1% of pre-provision profit, a ratio consistent with H1 FY26. This indicates that profit growth stemmed from core lending business expansion rather than a reduction in credit costs.
| Asset Quality | Sep-25 | Mar-26 | Sep-26 |
|---|---|---|---|
| Gross NPA (Stage 3) | 4.52% | 3.72% | 3.80% |
| Net NPA | 2.94% | 2.32% | 2.30% |
| Provision coverage (Stage 3) | 35.91% | 38.60% | 40.49% |
| Half-year provisions (₹ Cr) | 16.9 | 24.5* | 30.8 |
*Half-year provisions for Mar-26 represent H2 FY26.
Asset quality showed improvement year-over-year, with Gross NPA declining from 4.52% in September 2025 to 3.80% in September 2026. However, it experienced a slight uptick from 3.72% reported in March 2026. Net NPA also improved, falling to 2.30% from 2.94% a year ago.
Provision coverage for Stage 3 loans strengthened to 40.49%, up from 35.91% a year prior, indicating an increased buffer against potential defaults. On an annualised basis, H1 provisions equate to approximately 3.4% of the average loan book, reflecting a high credit cost environment.
The company confirmed that its Ind AS provisions exceed the requirements of RBI’s IRACP norms, eliminating the need for an impairment reserve.
Balance Sheet and Capital Position
The loan book expanded by 7.6% over six months to ₹1,882.1 crore. Total assets grew 14% to ₹2,328.8 crore.
| (₹ Crore) | Mar-26 | Sep-26 | Change |
|---|---|---|---|
| Loans | 1,749.3 | 1,882.1 | +7.6% |
| Cash and bank balances | 164.4 | 250.5 | +52% |
| Total assets | 2,035.8 | 2,328.8 | +14% |
| Debt securities (NCDs) | 195.4 | 238.8 | +22% |
| Bank and other borrowings | 1,152.9 | 1,389.3 | +21% |
| Deposits | 135.4 | 127.0 | -6% |
| Total borrowings | 1,483.7 | 1,755.1 | +18% |
| Net worth | 498.6 | 521.7 | +5% |
| Ratio | Sep-25 | Mar-26 | Sep-26 |
|---|---|---|---|
| Capital adequacy (CAR) | 20.51% | 25.09% | 21.74% |
| Debt to equity | 4.14x | 2.98x | 3.37x |
| Debt to total assets | 78.54% | 72.90% | 75.45% |
| Net worth (₹ Cr) | 339.6 | 498.6 | 521.7 |
Net worth increased by 5% sequentially to ₹521.7 crore, representing a 54% increase from ₹339.6 crore a year ago. Much of this growth stemmed from new equity raised between September 2025 and March 2026, which saw paid-up capital rise from ₹12.3 crore to ₹14.5 crore.
Leverage is trending upwards, with the debt-to-equity ratio increasing from 2.98x in March to 3.37x as total borrowings grew faster (+18%) than net worth (+5%). While capital remains comfortable at 21.74% CAR, it has decreased from 25.09% in March due to the pace of lending growth.
The higher cash and bank balances of ₹250.5 crore partly reflect new NCD proceeds. The company raised ₹50 crore through NCDs on September 30, 2026, which remained unutilized by the quarter end.
Key Monitoring Metrics
- Provisions in H2 FY27: H1 provisions of ₹30.8 crore already constitute 74% of FY26’s full-year provisions of ₹41.4 crore. The trajectory of provisions in the second half will be crucial for full-year profitability.
- Gross NPA Trend: While down year-over-year, the slight increase from 3.72% in March to 3.80% in September warrants attention.
- Full-Year Profit Achievement: With H1 profit at 67% of FY26’s total, performance in H2 will determine the extent of full-year growth.
- Leverage and Capital Adequacy: The decline in CAR from 25.1% to 21.7% within six months suggests that sustained high growth rates may necessitate further capital infusion.
Source: Berar Finance Ltd, unaudited financial results for the quarter and half year ended 30 September 2026, with Regulation 52(4) disclosures and the NCD utilisation statement. Approved by the board on 3 November 2026; limited review by N.A. Shah Associates LLP. All figures are in ₹ crore unless stated. NII, pre-provision profit, and cost ratios are calculated.
Latest Price : https://mrgaga.in/unlisted-share